

Q3 2026 Review of Shareholder Activism
Observations on the Activism Environment in 2026 YTD
1. Campaign Activity in Line with Prior Years Following Slower Q3
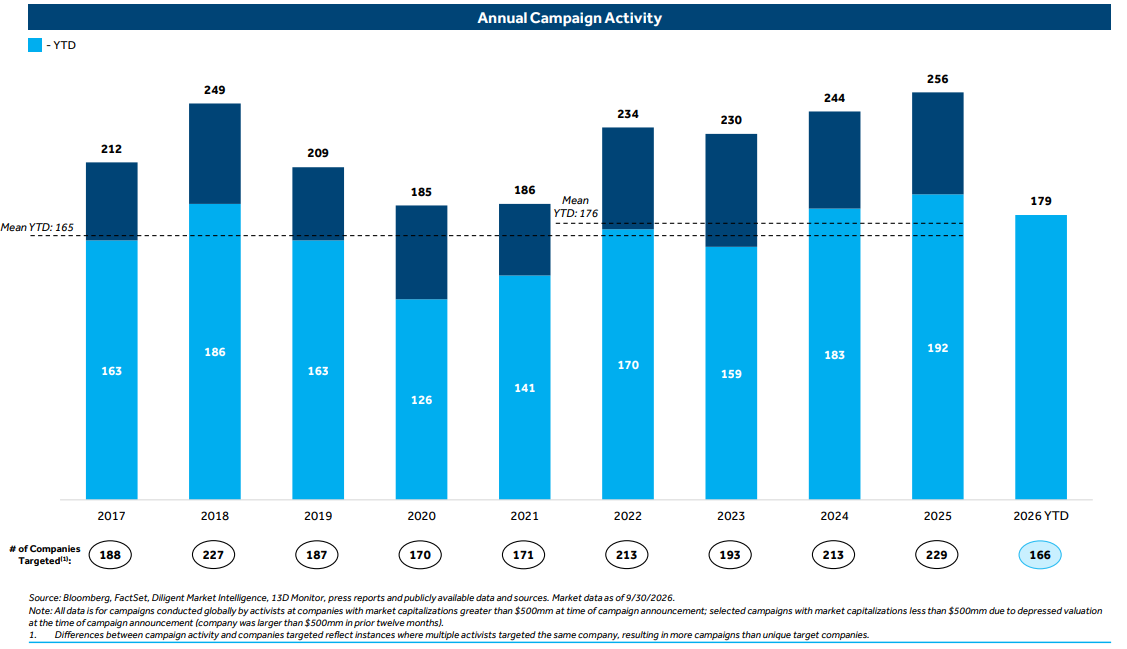
- 179 campaigns were launched in 2026 YTD, down 7% year over year (192), but largely in line with the four year average
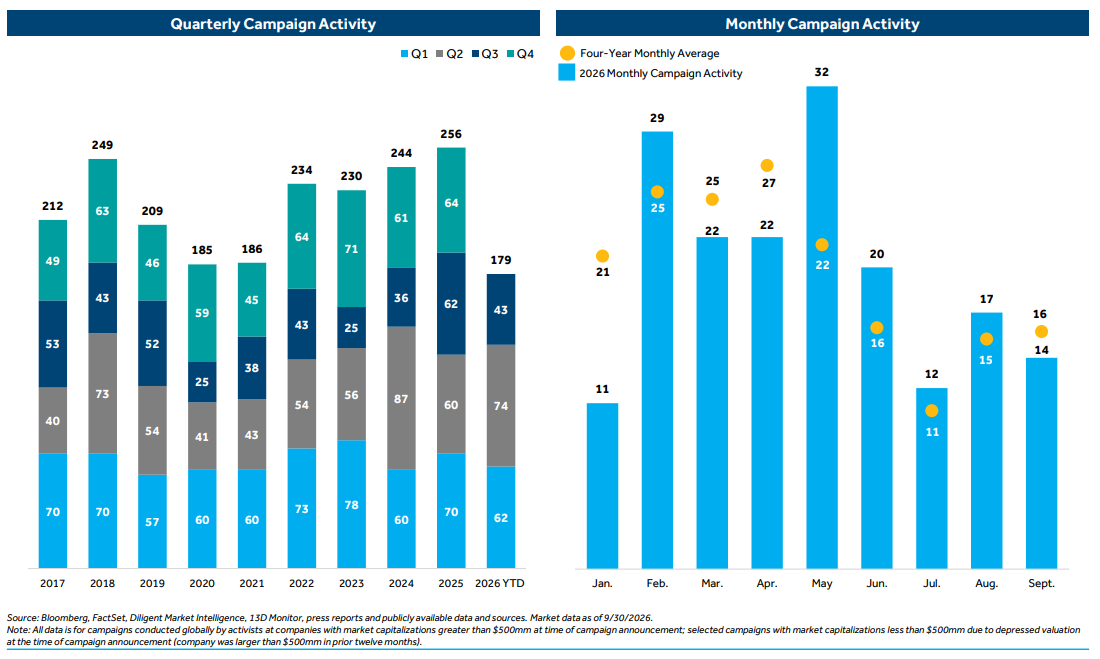
- 43 campaigns in Q3 represented a 42% drop from 74 in Q2, reflecting a more normal “seasonal slowdown” compared to what was an unusually busy Q3 2025 (62)
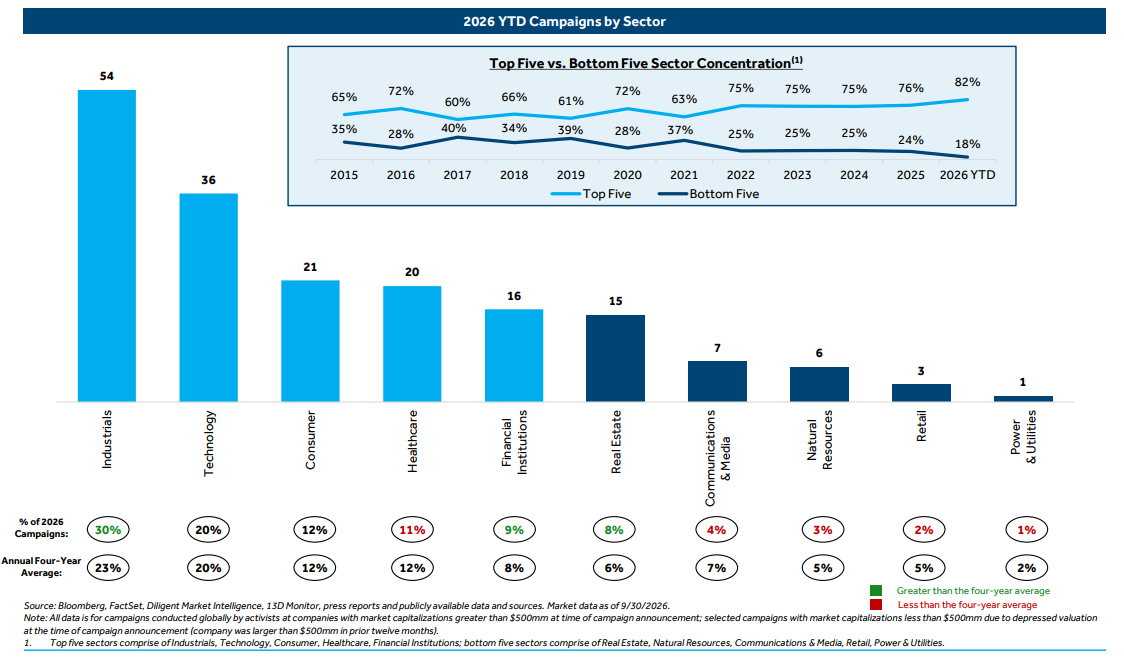
- A record level of concentration in the top five sectors targeted by activists (82%), led by Industrials (30%) and Technology (20%)
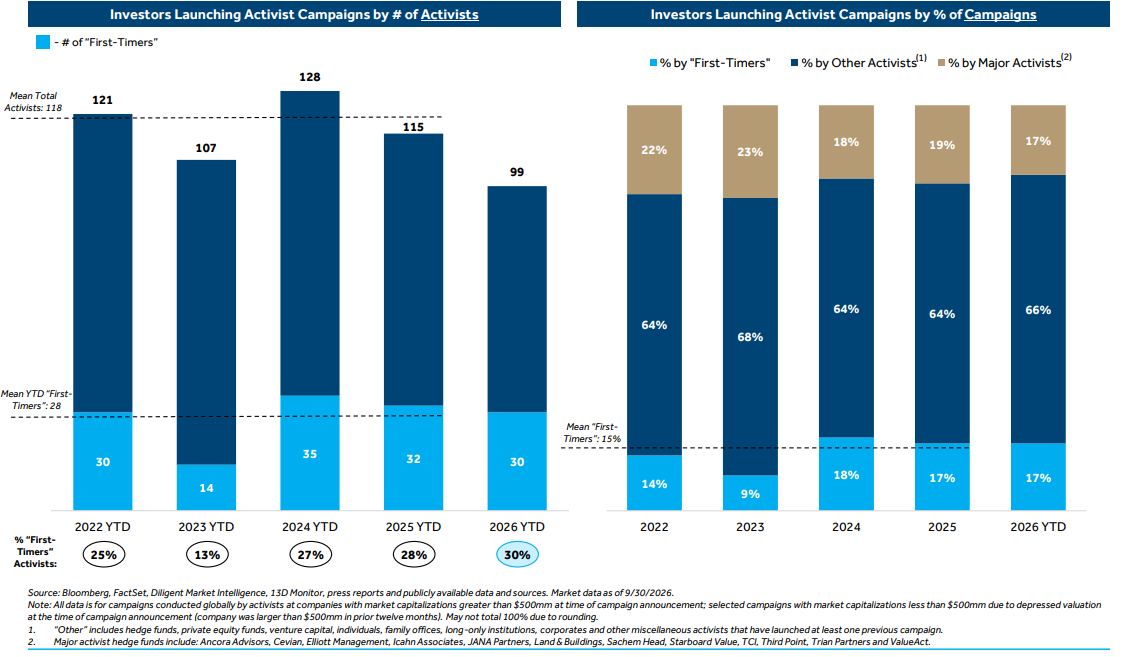
- The overall number of activists continued to track lower in 2026, down 14% year over year to 99
- Elliott launched the most campaigns YTD with 16 across seven countries; three of its Q3 launches were among the largest in 2026
2. APAC’s Share At Record High Led by Japan
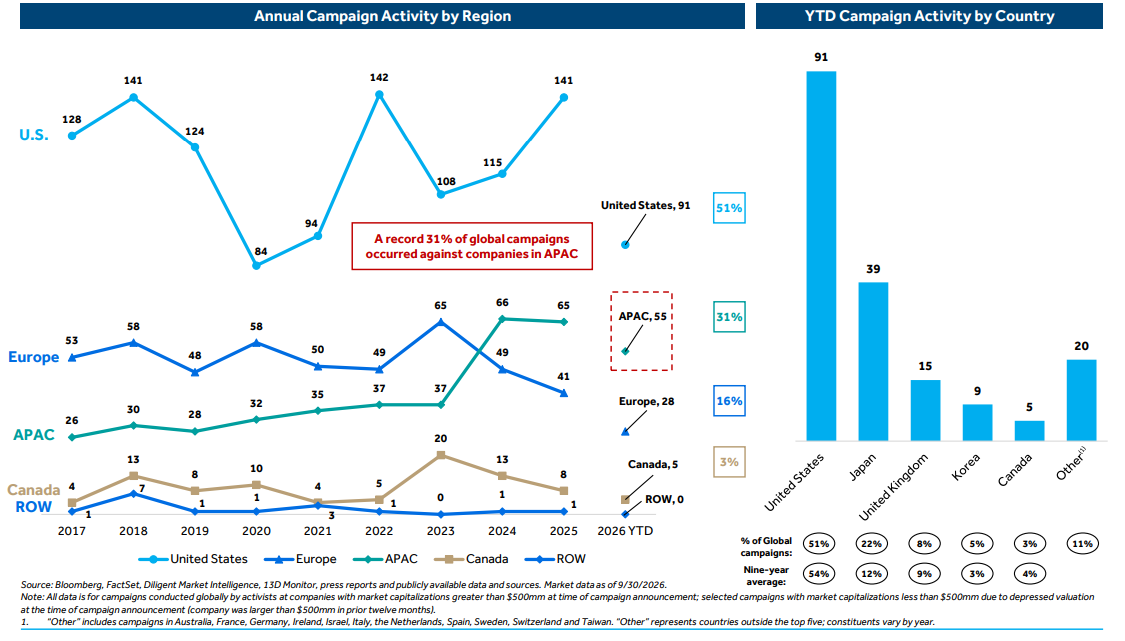
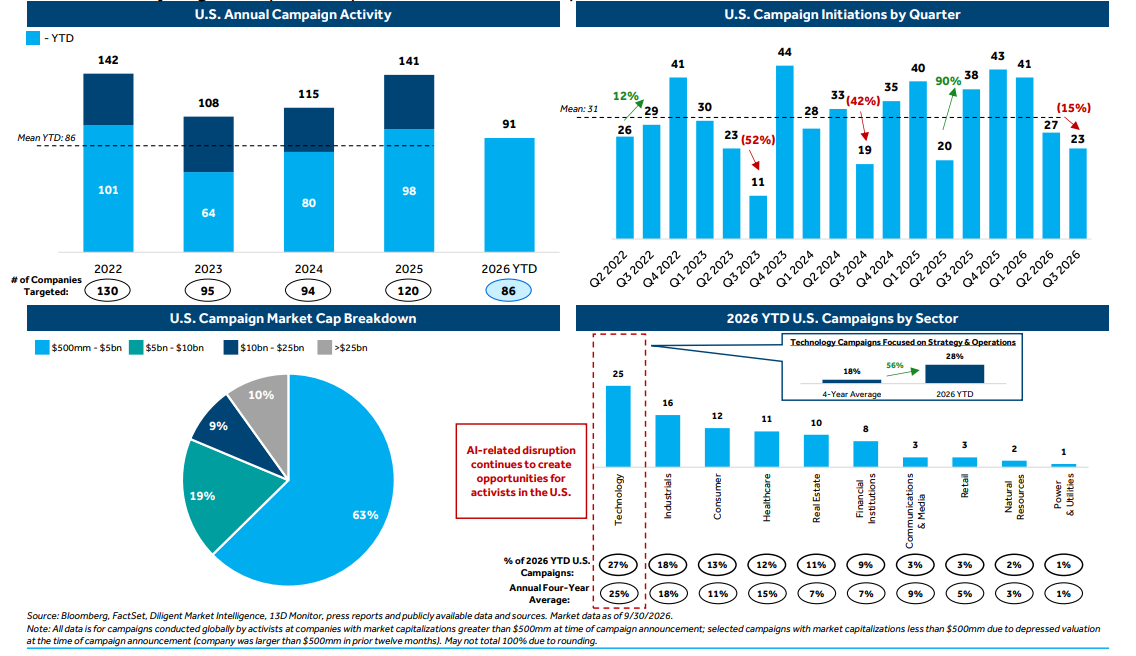
- The U.S. remained the primary market for activism with 91 campaigns (51% share of global activity), above its four year YTD average of 86
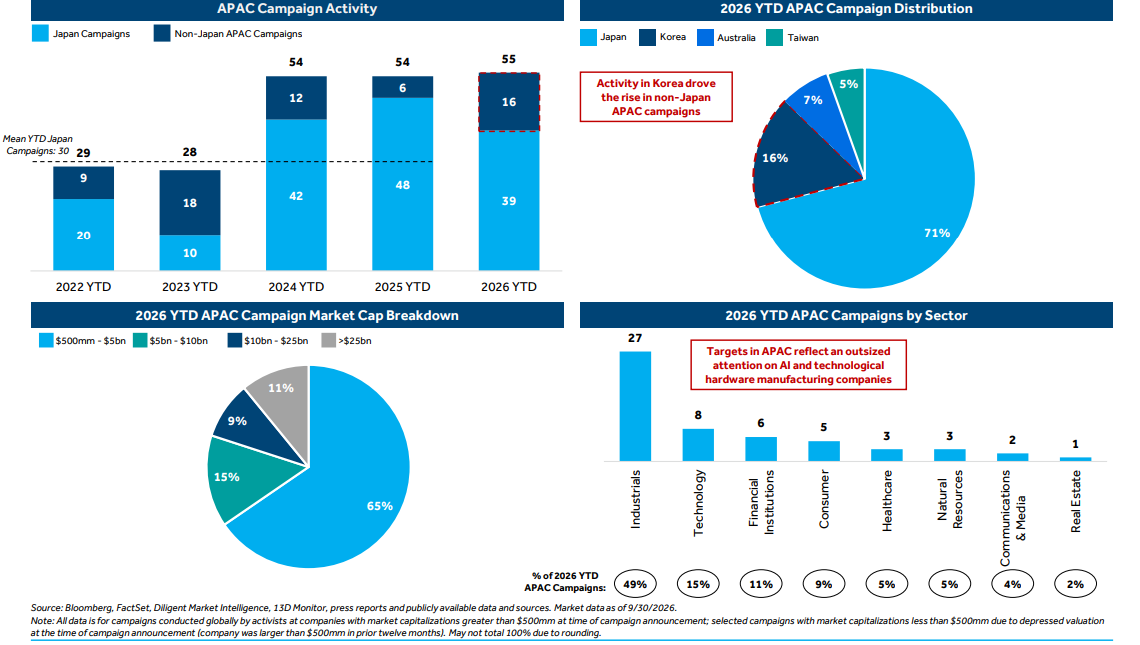
- 55 campaigns in APAC represented a record 31% share; activity in the region remained on pace with recent years, driven by outsized attention on AI and technological hardware manufacturing
- Activity in Japan continued to be the main contributor, but activism in other regions picked up (Korea, Australia and Taiwan)
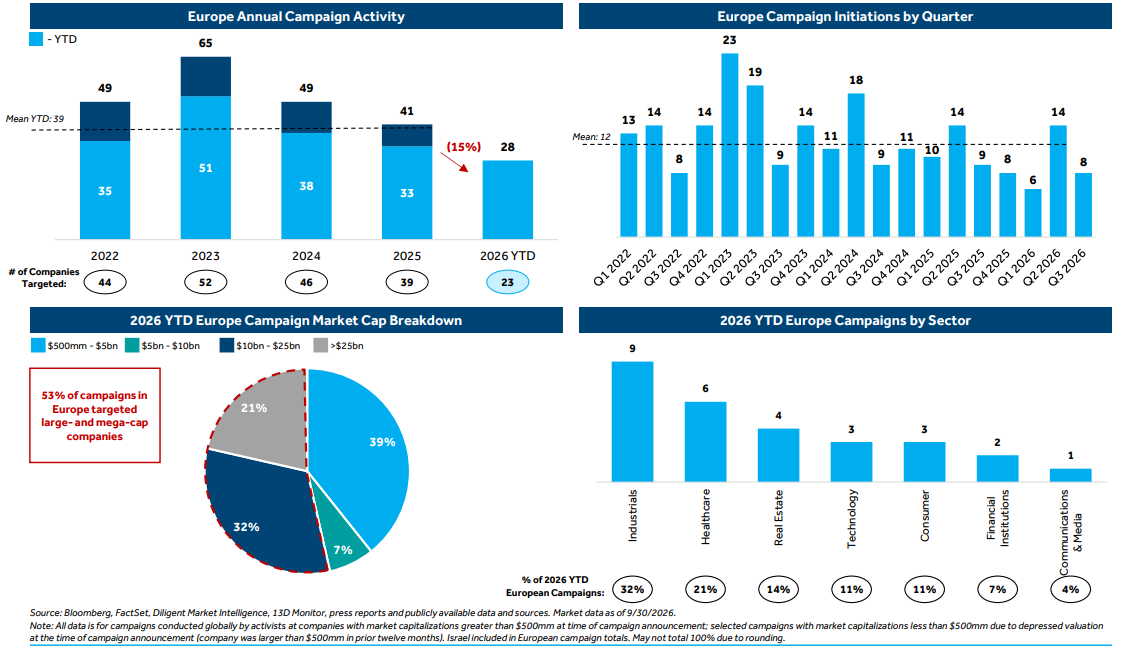
- 28 campaigns in Europe were down 15% year over year (33) and on pace for a third consecutive year of annual declines; the U.K. continued to represent the majority of activity (54%)
- Seven of the 10 largest campaign targets were located outside the U.S., including the largest target of 2026, Samsung Electronics (Korea)
3. M&A Accounted for Over Half of Q3 Demands
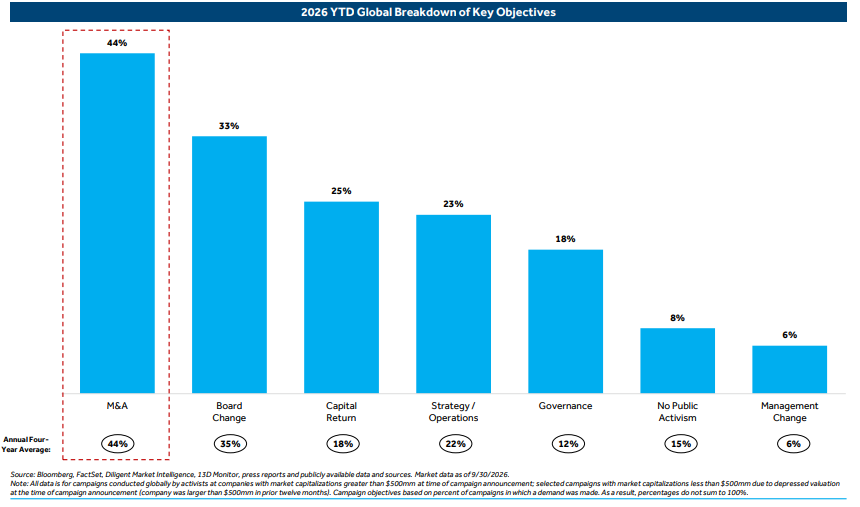
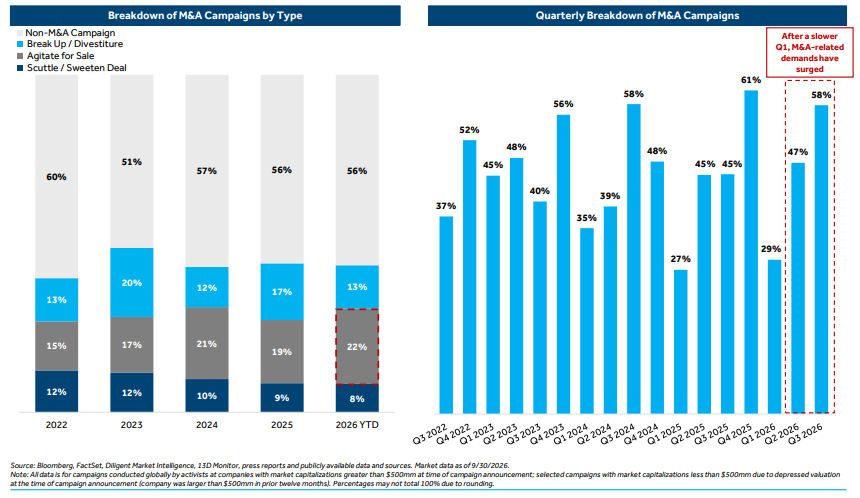
- 58% of Q3 demands were M&A related; the surge of M&A demands lifted the YTD mark to 44% of all demands, now in line with the four year average after a slow start to the year
- A record 22% of demands specifically focused on the target selling itself (e.g., Bath & Body Works, Knife River and Independence Realty)
- Activists continued to tip targets into private equity sales in Q3, reflecting an ongoing interest in alignment
4. Leading Activists Dominated Board Seat Wins
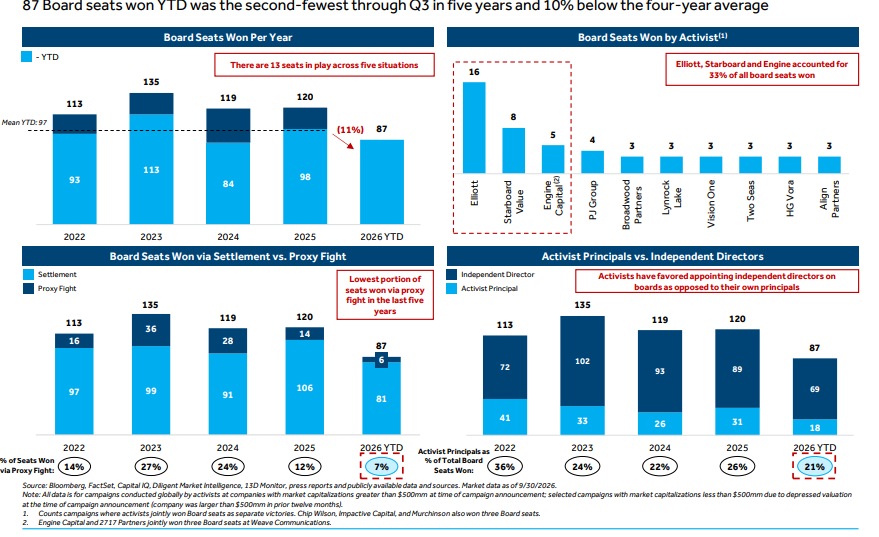
- Activists won 87 board seats YTD, 10% below the four year average, with wins concentrated among Elliott, Starboard and Engine, which accounted for one third of the total
- The lower number of board seats was due to fewer U.S. settlements and contested fights
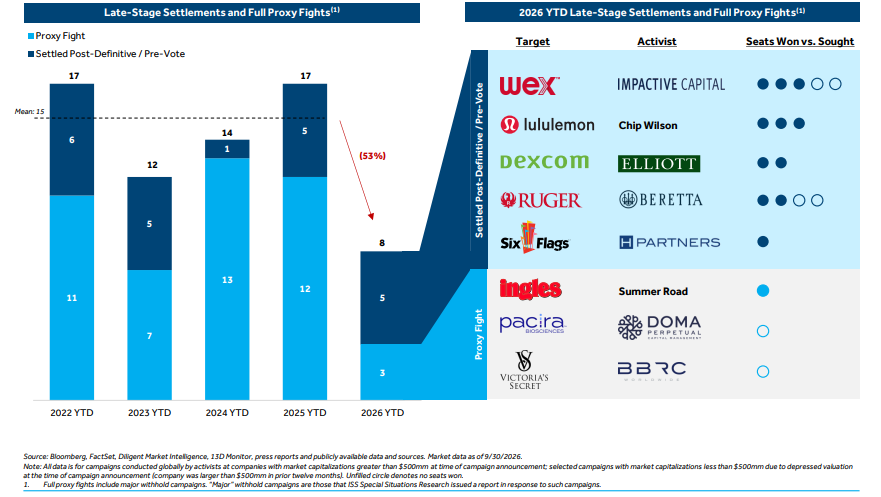
- There have been just eight late stage settlements and full proxy fights[1] in 2026 YTD, compared to 17 in 2025 YTD, a 53% decline
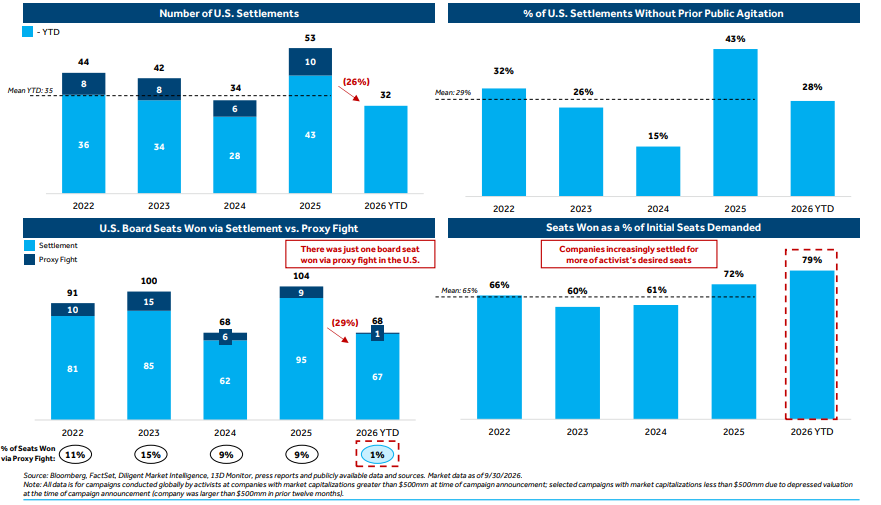
- 32 settlements at U.S. companies (down 26% year over year) resulted in 67 board seats won
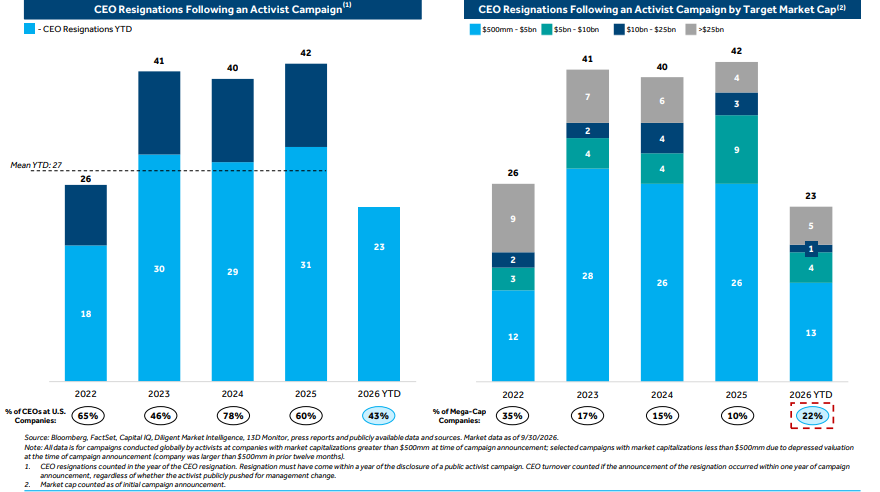
- 23 CEOs resigned following activist campaigns[2], lower year over year, with nearly a quarter occurring at mega caps
5. Legal and Regulatory Dynamics
- The SEC proposed rescinding Rule 14a-8 and amending Rule 14a-4, expanding issuer discretion over shareholder proposals
- A separate SEC proposal would shorten the broker search period, compressing contested vote timelines
- New SEC guidance confirmed Schedule 13G filers can engage with issuers without losing passive eligibility
- Proxy advisors under fire. DOJ withdrew its ISS antitrust letter; Texas sued Glass Lewis; SEC sued ISS over a subpoena
Campaign Activity Moderated After a Busy First Half
179 campaigns YTD were down 7% year over year, though largely in line with the four year YTD average. The nine year mean YTD was 165 campaigns and the four year mean YTD was 176 campaigns.
Campaign Activity by Quarter and Month
Q3 activity was down 42% sequentially, in line with typical seasonal norms.
Geographic Breakdown
APAC expanded global share as the United States continues to lead. A record 31% of global campaigns occurred against companies in APAC.
Sector Concentration of Campaigns at Record Levels
82% of campaigns have occurred at companies in five sectors, a record high level of concentration.
Activist Targets by Company Size
While the U.S. remains the primary forum for activism, seven of the 10 largest campaign targets were located outside the U.S.
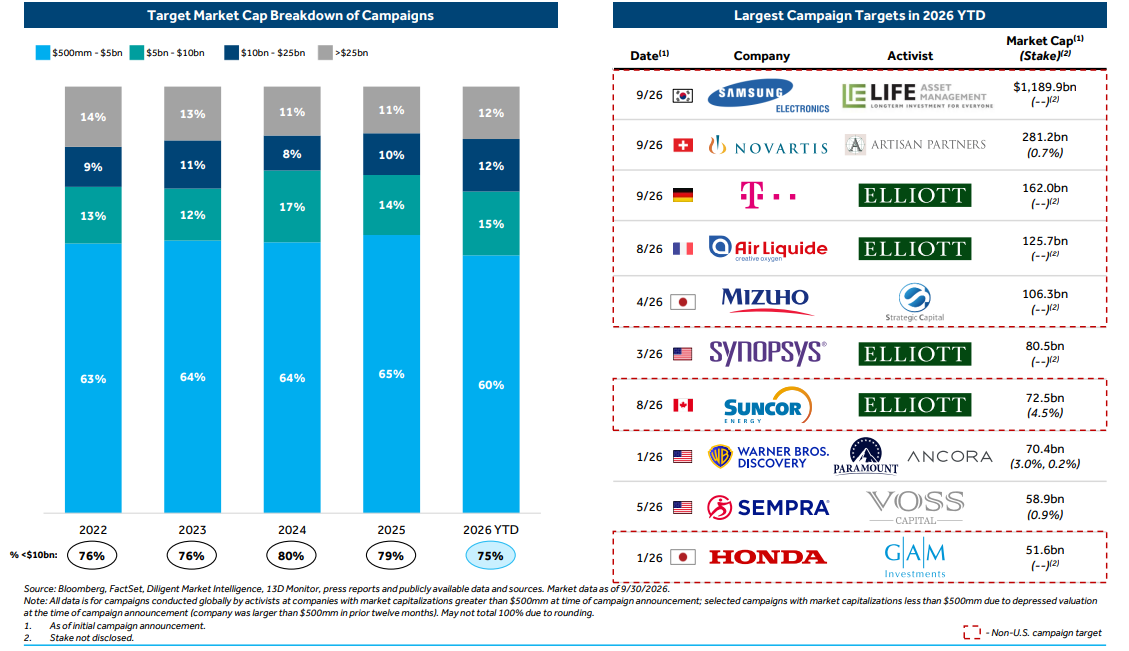
Notable Q3 2026 Campaign Launches and Developments
Notable Launches
| Launch Date | Activist | Company | Market Cap[8] | Highlights |
|---|---|---|---|---|
| September 2026 | Elliott | Deutsche Telekom (Germany) | $162.0bn | In September, Elliott reportedly opposed Deutsche Telekom’s potential merger with T-Mobile US and urged the Company to pursue alternative value creation measures, including larger share buybacks. |
| August 2026 | Engine Capital | EPAM (U.S.) | $6.1bn | In August, Engine Capital argued that EPAM’s valuation discount was excessive even amid an IT services sector weighed down by AI disruption fears. It urged the Company to pursue share repurchases, strengthen executive and Board alignment with shareholders, or initiate a sale. |
| August 2026 | Starboard Value | Shake Shack (U.S.) | $3.0bn | In August, Starboard Value urged Shake Shack to accelerate its U.S. expansion through increased franchising, arguing that a more capital efficient model could accelerate development and enhance shareholder value. |
| August 2026 | Elliott | Air Liquide (France) | $125.7bn | In August, Elliott built a stake in Air Liquide and reportedly urged management to narrow its margin gap with industrial gas peers. |
Notable Developments
| Launch Date | Activist | Company | Market Cap[8] | Highlights |
|---|---|---|---|---|
| June 2026 | Oasis | Vail Resorts (U.S.) | $5.2bn |
|
| June 2026 | Lauro and Palliser | SEGRO (U.K.) | $12.9bn |
|
| May 2026 | Ancora and Engine Capital | H.B. Fuller (U.S.) | $3.3bn |
|
| April 2026 | TOMS Capital Investment Management | Voya (U.S.) | $7.3bn |
|
Top 10 Activists of 2026 YTD
Elliott has launched 16 campaigns across seven jurisdictions, targeting companies that are on average about $41bn in market cap. The top three activists accounted for 18% of YTD campaigns, and the top 10 together accounted for 39% of all 2026 YTD campaigns.
| Rank | Activist | Base | Average Target Market Cap | YTD / Q3 2026 Campaigns Launched | 2026 YTD Target Companies | 2025 Campaigns Launched / Rank |
|---|---|---|---|---|---|---|
| 1 | Elliott | U.S. | $40.6bn | 16 / 4 | Air Liquide, Align, Bio-Rad, Bunzl, CCC, Daikin, Deutsche Telekom, Dexcom, LSEG, MOL, NX Nippon Express, Northern Star, Norwegian Cruise Line, Suncor, Synopsys, The J.M. Smucker Co. | 18 / 1 |
| 2 | Oasis | Hong Kong | $2.7bn | 9 / 1 | Comsys Holdings, EXEO Group, Infomart, Kadokawa, Mirait One, Tokyo Steel Manufacturing, Vail Resorts, SMS | 12 / 2 |
| 3 | Palliser | U.K. | $13.5bn | 8 / 2 | Ajinomoto, Autotrader, Intertek, Recordati, SEGRO, SMC, TOTO, WUS Printed Circuit Co., Ltd. | 6 / 7 |
| T4 | Starboard Value | U.S. | $6.6bn | 7 / 2 | CarMax, Dynatrace, Flowserve, Knife River, Lamb Weston, Shake Shack | 8 / T3 |
| T4 | Dalton Investments | U.S. | $5.9bn | 7 / 0 | Anicom Holdings, Bunka Shutter, Meiji, Nitta, Secom, Shimano, Yakult | 5 / T8 |
| 6 | Irenic Capital Management | U.S. | $11.0bn | 6 / 1 | HPE, Independence Realty Trust, Ralliant, Snap, SPS Commerce, Teleflex | 5 / T8 |
| 7 | Engine Capital | U.S. | $3.1bn | 5 / 2 | EPAM, Fox, H.B. Fuller, KBR, Weave | 7 / T5 |
| T8 | Bradley Radoff | U.S. | $0.6bn | 4 / 1 | Avanos, Cerus, Marston’s, Redwood Trust | 1 / NR |
| T8 | Align Partners Capital Management | Korea | $3.9bn | 4 / 2 | BNK Financial Group, DB Insurance, JB Financial Group, Solum | 1 / NR |
| T8 | Holdco Asset Management | U.S. | $0.9bn | 4 / 0 | Capitol Federal, Central Pacific Bank, Heritage Commerce Corp, Trustco Bank | 7 / T5 |
| Top 10 Total | 70 / 15 | 39% of all 2026 YTD campaigns |
T means tied for the rank shown. NR means not ranked.
Global Activist Universe
Number of funds engaging in activism continued to pace lower year over year. The mean total number of activists was 118 and the mean YTD number of first timers was 28.
U.S. Campaign Activity
U.S. campaign activity remained in line with recent years; the technology sector continued to be the most popular pick for activists as they target companies exposed to AI related disruption.
APAC Campaign Activity
Activity in APAC reached a record high; Japan continued to drive the bulk of activism in the region but 16 non Japan campaigns contributed to the high watermark.
Europe Campaign Activity
2026 is on track to mark a third consecutive year of declining activist activity in Europe (28 campaigns, down 15%).
European Activity by Country
Activism in the U.K. represented over half of the activity in Europe.
| Country | % of European Activist Campaigns | 2026 YTD Campaigns | 2025 YTD Campaigns | Change | Selected Targets |
|---|---|---|---|---|---|
| United Kingdom | 54% | 15 | 13 | Up | Autotrader, CVS Group, Barratt Redrow, Bunzl, LSEG, SEGRO, Intertek |
| Germany | 7% | 2 | 4 | Down | Deutsche Telekom, Evotec |
| Ireland | 7% | 2 | 2 | Unchanged | Irish Continental Group |
| Israel | 7% | 2 | 0 | Up | InMode, Nano Dimension |
| Italy | 7% | 2 | 3 | Down | Leonardo, Recordati |
| France | 4% | 1 | 2 | Down | Air Liquide |
| Netherlands | 4% | 1 | 4 | Down | Heineken |
| Spain | 4% | 1 | 1 | Unchanged | Indra |
| Sweden | 4% | 1 | 0 | Up | Essity |
| Switzerland | 4% | 1 | 0 | Up | Novartis |
Key Campaign Objectives in 2026 YTD
Activists continue to favor M&A demands over operational fixes.
Global M&A Campaign Activity
Activists have increasingly called for targets to sell themselves; this demand type represented a majority of all M&A related demands.
CEO Resignations
Global CEO resignations following an activist campaign were lower than recent years; mega cap companies represent nearly a quarter of these events.
Global Board Seats Won by Activists
87 board seats won YTD was the second fewest through Q3 in five years and 10% below the four year average.
U.S. Settlements
32 settlements were down 26% year over year.
Contextualizing the 2026 YTD U.S. Proxy Season
Thus far in 2026, there have been only eight late stage settlements (post definitive proxy, pre final vote) and full proxy fights in the U.S., down 53% vs. 17 in 2025 YTD.
Considerations for Q4 and Beyond
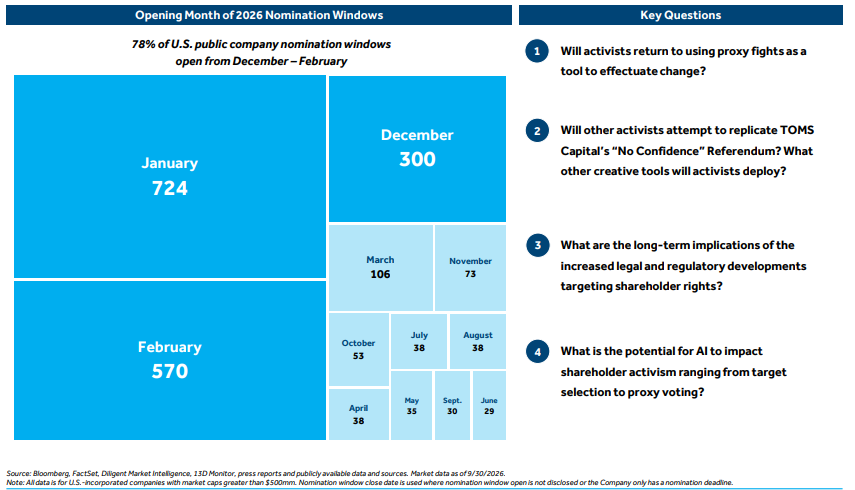
After an exceptionally quiet proxy season, time will tell whether typical seasonal trends will hold true.
Regulatory and Ecosystem Developments Impacting Activism
SEC Proposes Rescinding Rule 14a-8
- In mid August, the SEC said it would permanently discontinue responding to Rule 14a-8 no action requests and has since proposed rescinding the rule as exceeding its statutory authority
- In a corresponding move, and in a way to combat proposals that will move directly to the floor of Annual Meetings, the SEC introduced a companion amendment to Rule 14a-4 that would give companies expanded discretionary voting authority, unless a shareholder opts out, over proposals presented at a meeting but off the company’s proxy card
SEC Moves to Modernize Proxy Delivery and Solicitation
- Proposed amendments would eliminate annual report delivery and Notices of Exempt Solicitation, drop the 20 business day advance delivery rule and shorten the broker search period to five business days
- A separate proposed Regulation E Delivery would permit broader electronic delivery without investor consent; a shorter broker search and the loss of exempt solicitation notices would compress contested vote timelines
SEC Clarifies Schedule 13G Eligibility for Engagement
- New Corporate Finance Interpretations, or CFIs, confirm a Schedule 13G filer can engage in discussions with an issuer that are a) initiated by the issuer; b) responsive to a request from the issuer to understand the shareholders’ voting decisions at previous meetings; or c) initiated by the shareholder solely to understand the issuer’s disclosures or other public communications
- Eligibility remains case by case, but the updated guidance should restore engagement that slowed after the SEC’s rule change regarding Schedule 13G/13D eligibility
Proxy Advisors Under Continued Federal and State Pressure
- The DOJ Antitrust Division withdrew its 1987 Business Review Letter to ISS, which had said it had no current intention to bring antitrust action against the firm, as no longer reflecting ISS’s practices
- The withdrawal follows the executive order Protecting American Investors From Foreign Owned and Politically Motivated Proxy Advisors, which directs the FTC to review state antitrust investigations
- Texas sued Glass Lewis under its Deceptive Trade Practices Act, following a parallel suit against ISS in May; Florida and Missouri actions remain live, and the SEC sued ISS in September to enforce a subpoena
Source. Bloomberg, FactSet, Capital IQ, Diligent Market Intelligence, 13D Monitor, Dealogic, press reports and publicly available data and sources. Market data as of September 30, 2026. The regulatory and ecosystem developments section draws on press reports and public filings.
Note. All data is for campaigns conducted globally by activists at companies with market capitalizations greater than $500mm at time of campaign announcement; selected campaigns with market capitalizations less than $500mm due to depressed valuation at the time of campaign announcement (company was larger than $500mm in prior twelve months). Percentages may not total 100% due to rounding. In the European data, Israel is included in European campaign totals.
1Full proxy fights include major withhold campaigns. “Major” withhold campaigns are those that ISS Special Situations Research issued a report in response to such campaigns.(go back)
2CEO resignations counted in the year of the CEO resignation. Resignation must have come within a year of the disclosure of a public activist campaign. CEO turnover counted if the announcement of the resignation occurred within one year of campaign announcement, regardless of whether the activist publicly pushed for management change.(go back)
3Differences between campaign activity and companies targeted reflect instances where multiple activists targeted the same company, resulting in more campaigns than unique target companies.(go back)
4“Other” includes campaigns in Australia, France, Germany, Ireland, Israel, Italy, the Netherlands, Spain, Sweden, Switzerland and Taiwan. “Other” represents countries outside the top five; constituents vary by year.(go back)
5Top five sectors comprise of Industrials, Technology, Consumer, Healthcare and Financial Institutions; bottom five sectors comprise of Real Estate, Natural Resources, Communications & Media, Retail and Power & Utilities.(go back)
6As of initial campaign announcement.(go back)
7Stake not disclosed.(go back)
8Market cap as of campaign announcement date, or as of initial date of disclosure. In the case of multiple activists, represents market cap as of earliest campaign announcement date or initial disclosure.(go back)
9“Other” includes hedge funds, private equity funds, venture capital, individuals, family offices, long only institutions, corporates and other miscellaneous activists that have launched at least one previous campaign.(go back)
10Major activist hedge funds include Ancora Advisors, Cevian, Elliott Management, Icahn Associates, JANA Partners, Land & Buildings, Sachem Head, Starboard Value, TCI, Third Point, Trian Partners and ValueAct.(go back)
11CEO resignations counted in the year of the CEO resignation. Resignation must have come within a year of the disclosure of a public activist campaign. CEO turnover counted if the announcement of the resignation occurred within one year of campaign announcement, regardless of whether the activist publicly pushed for management change.(go back)
12Market cap counted as of initial campaign announcement.(go back)
13Counts campaigns where activists jointly won Board seats as separate victories. Chip Wilson, Impactive Capital and Murchinson also won three Board seats.(go back)
14Engine Capital and 2717 Partners jointly won three Board seats at Weave Communications.(go back)
15Full proxy fights include major withhold campaigns. “Major” withhold campaigns are those that ISS Special Situations Research issued a report in response to such campaigns.(go back)
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
